Gamma Distribution
Gamma Distribution
A random variable is said to have a Gamma distribution if for parameters \((\alpha, \lambda)\) with \(\lambda > 0\) (called the rate) and \(\alpha > 0\) (called the shape), it has the following probability distribution
where the denominator is defined as
Note that at \(\alpha = 1\), \(\Gamma (1) = \int_{0}^{\infty} e^{-x} = 1\). Hence, if \(\alpha\) is an integer, \(\Gamma(\alpha) = (\alpha-1) !\) using the recursion relation derived above.
For a fixed \(\lambda\), as the value of \(\alpha\) becomes large, the distribution takes the form of a normal distribution.
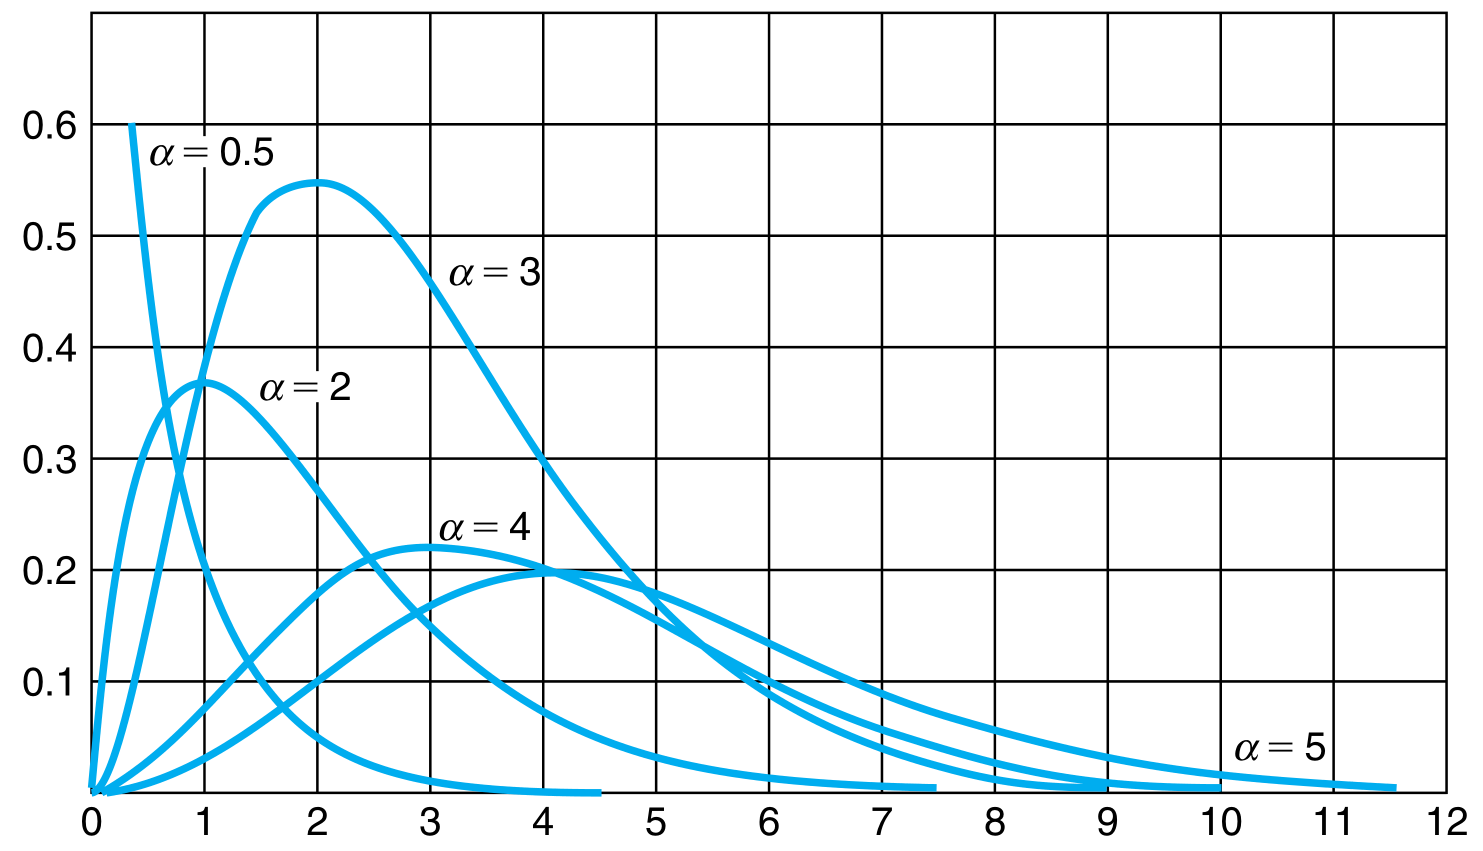
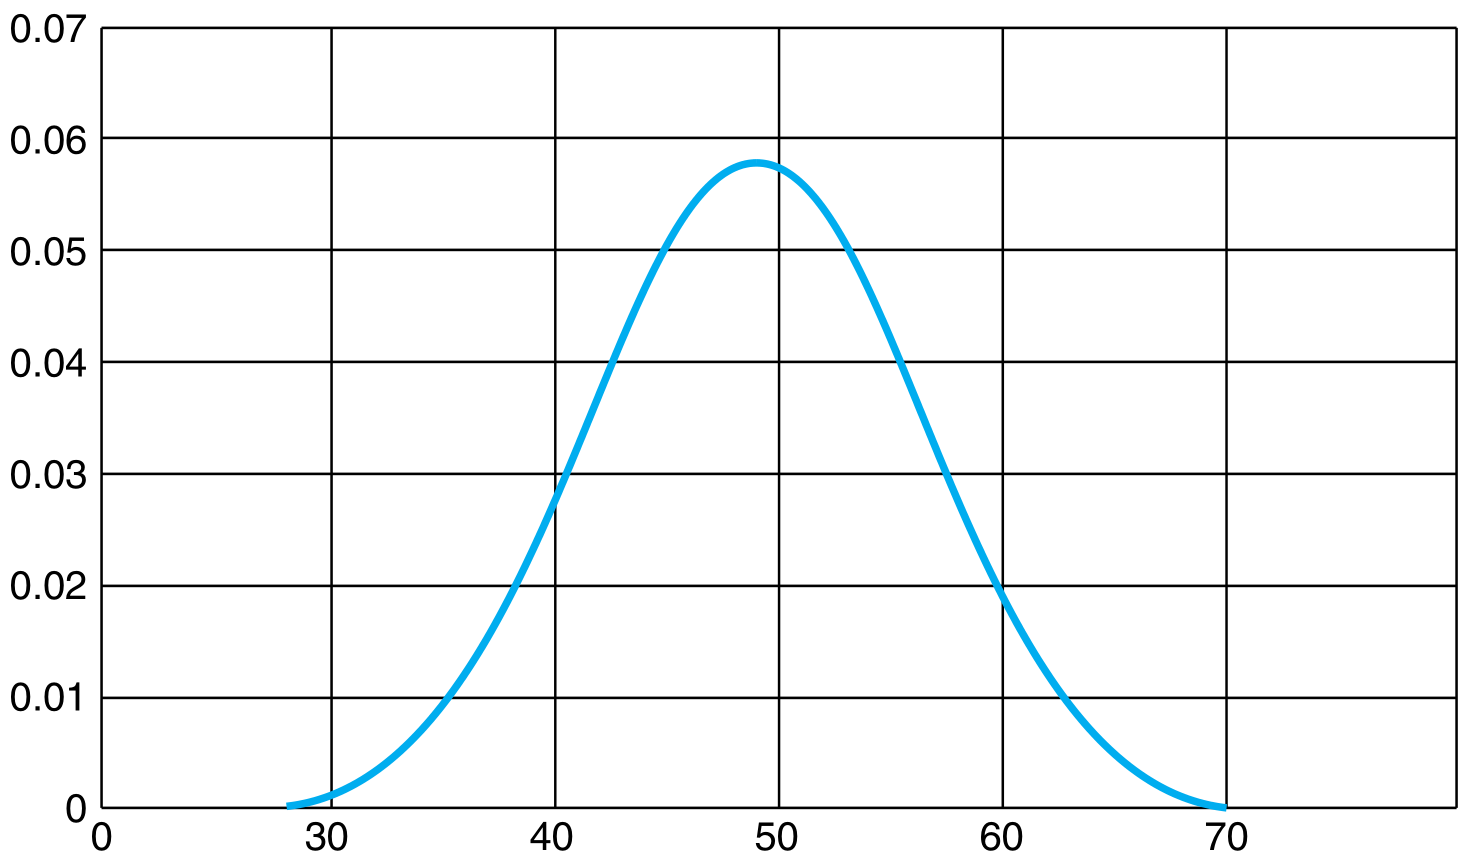
There is an alternate formulation of the Gamma distribution where \(\beta\) is used instead of \(\lambda\), with \(\beta = 1/\lambda\) and \(\beta\) is called the scale parameter.
Mean, Variance and Moment Generating Function
Mean and variance are easily obtainable for this using the moment generating function. Recall
For the current distribution,
by rearranging the terms to complete an integral of a Gamma distribution with parameters \((\alpha, \lambda - t)\). Differentiating,
Sum of Gamma Distributions
Let \(X_{1}, X_{2}, \ldots, X_{n}\) be \(n\) independent random variables that are gamma distributed with parameters \((\alpha_{1}, \lambda), (\alpha_{2}, \lambda), \ldots, (\alpha_{n}, \lambda)\). Then the distribution of the sum of these random variables is itself a gamma distribution with the parameters \(\alpha^{\prime} = \sum_{i=1}^{n} \alpha_{i}\) and \(\lambda^{\prime} = \lambda\).
This follows from the moment generating function of the sum of variables
which is the moment generating function of \(Gamma(\sum_{i=1}^{n} \alpha_{i}, \lambda)\).
Relation with Exponential Distribution
With \(\alpha = 1\), the Gamma distribution becomes an Exponential distribution with parameter \(\lambda\). Based on the previous theorem, the sum of \(n\) independent Gamma distributed random variables with parameters \((1, \lambda)\) or equivalently, \(n\) independent Exponentially distributed random variables with parameter \(\lambda\) is a Gamma distribution with parameters \((n, \lambda)\).